What does ejerskifteforsikring cover?
Hidden damage that existed on the handover day and is not mentioned in the tilstandsrapport or the elinstallationsrapport. A typical basic policy runs for 5 years and can be extended to 10 (in a 2026 offer from one of the large insurers that cost 50% extra).
Price: usually DKK 15,000-35,000, and the seller pays half (Bolius). You must take it out no later than the handover day (Ældre Sagen).
What does ejerskifteforsikring not cover?
- Anything already written in the reports. A red item in the tilstandsrapport is your cost, not the insurer's. Many buyers do not know this.
- What is typical for the age of the house. For example a damp basement because of weak insulation that was standard at the time.
- External causes. Damp because there is no perimeter drain around the foundation.
- Parts that were not inspected. If the surveyor could not get into an area, the insurer can point to that.
- Sewers and underground pipes. Often only as an add-on (in the example: "illegal sewer pipes and joints" at extra cost).
- Soil contamination, for example from an oil tank. Also an add-on, in the example with a payout of up to DKK 500,000.
- Your own excess. In the example DKK 5,300 per claim, at most DKK 53,000 over the whole period.
The more red items in the report, the less the insurance protects you. A seller with an "honest" report where everything is written down effectively moves those risks onto you: they are already "known", and the known cannot be insured.
If you decline the insurance, the seller is still released from liability once he has offered it and is willing to pay half. Declining saves your half of the premium but leaves you without protection against hidden defects.
Why does ejerskifteforsikring reject so many claims?
It is the buyer who must prove the claim is covered. The hardest cases involve damp and mould: experts often disagree on the cause and on whether the damage existed before the purchase (Bolius).
This is how it looks in real life:
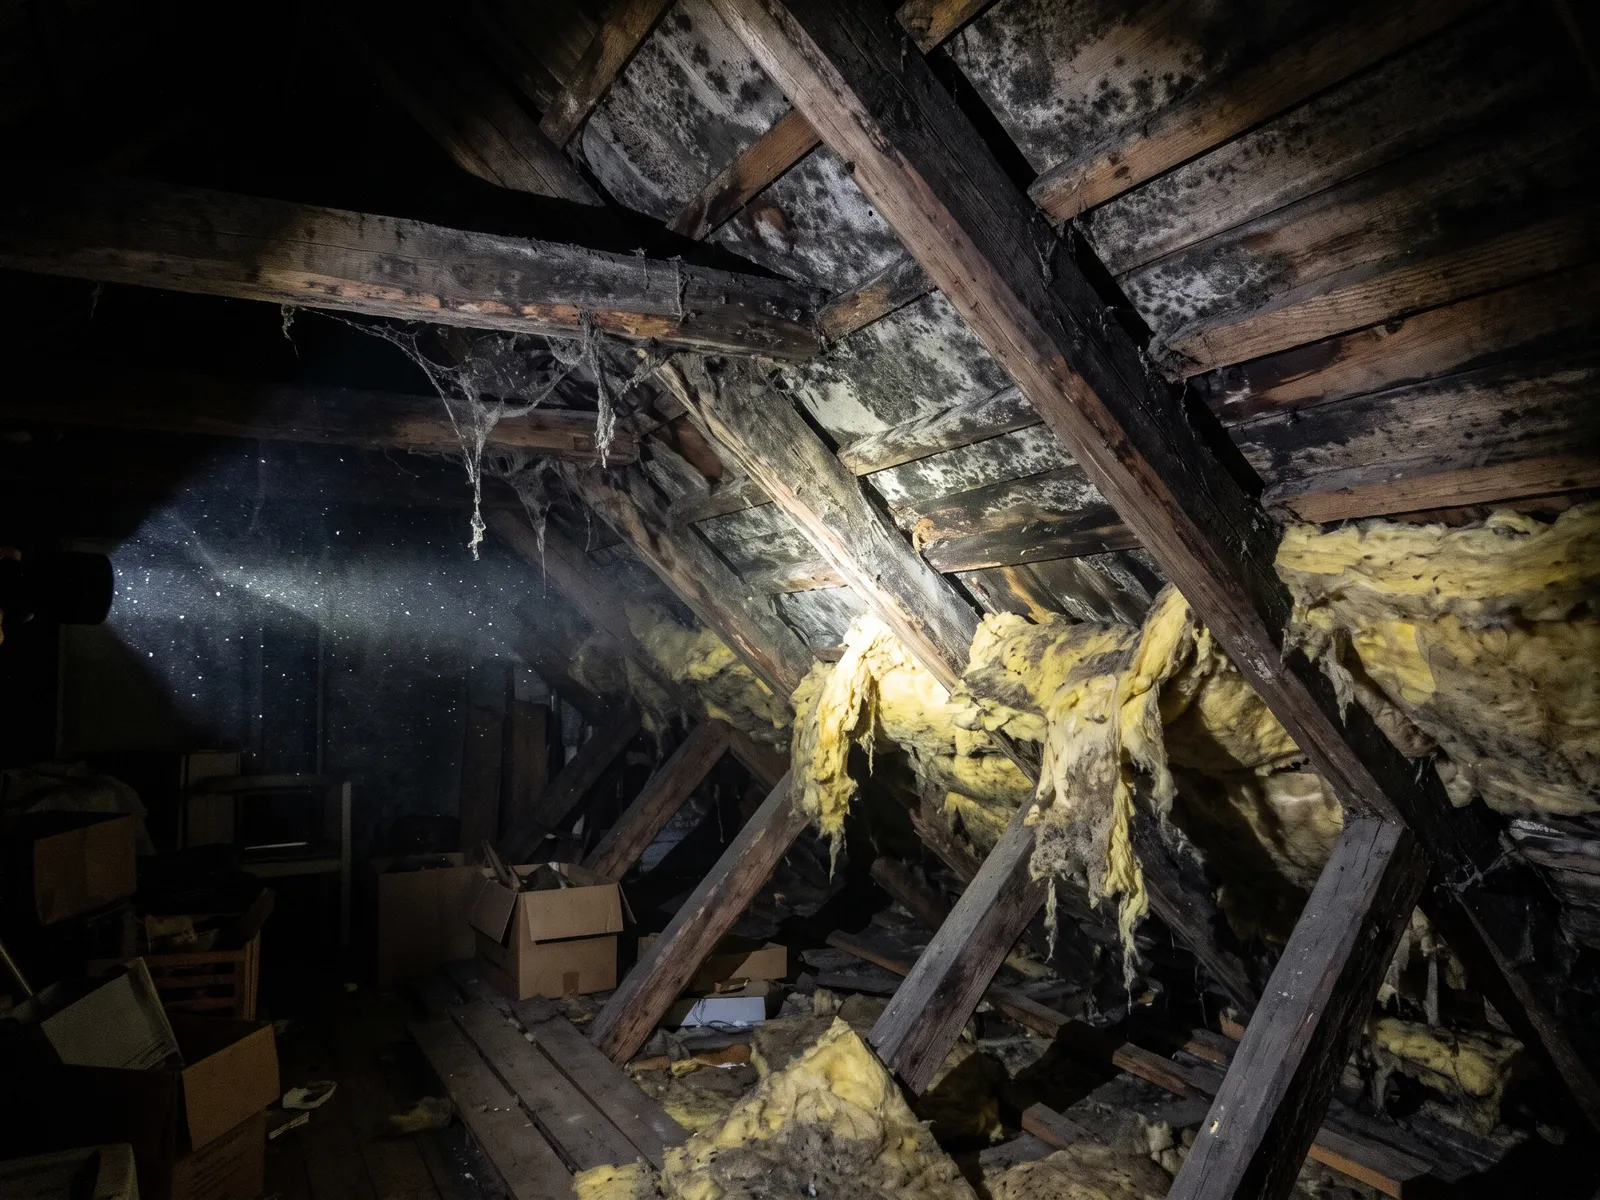
- The loft that was not inspected. The surveyor wrote "not inspected: no access". A year after the purchase, mould appears on the bedroom wall. It turns out the loft has been leaking for a long time, the ventilation could not cope and the damp went into the wall. The insurer replies: the area was not inspected, and how long this has been going on is unknown. Proving the problem existed before the purchase is almost impossible.
- The partly replaced roof. The seller replaced a section of roof, and in the report the roof is "fine". But the wall under that section was already damp, the moisture could not get out and went deeper. Two years later there is mould inside the wall. The insurer argues: is this the result of an old leak that "could be seen", or a new problem? The experts write different conclusions, and the case drags on for months.
In both cases the problem is real, but there is no payout, or only a partial one. That is why areas marked "not inspected" and traces of old repairs must be checked before you sign, not after.
Calculator: what do you pay yourself, even with insurance?
Your share of the premium and the excess
The excess in the example comes from a 2026 offer from one of the large insurers. Anything already written in the reports is not covered: that is 100% your cost.
According to Forsikring & Pension, ejerskifteforsikring pays out in only 3 cases out of 10. For ordinary home insurance it is 7-8 out of 10. In 2022 about 20% of the 1,526 complaints to Ankenævnet for Forsikring concerned ejerskifteforsikring: the most of any type of insurance.
Share of claims paid. Source: Forsikring & Pension via Bolius.
Fresh paint can cost you the insurance. The surveyor does not assess cosmetics, and a damp stain under new paint may not make it into the report. When the stain shows through, the insurer will ask: couldn't it be seen? Photograph ceilings and walls at the viewing: that is your evidence of the condition on the day you bought.
An example from our data
In 52 of 76 condition reports we reviewed (HUSDATA, North Jutland), part of the house was not inspected or only partly inspected. That is exactly where surprises hide most often, and exactly where the insurance is weakest.
The point: the insurance covers the unknown. So the known, from the documents, has to go into the price before you sign.
What should you check before taking out ejerskifteforsikring?
- The list of red and yellow items: these are your future costs.
- Areas "not inspected": ask for access or a separate inspection.
- Traces of old repairs: what was replaced, when and why (especially roof and wet rooms).
- Policy length: 5 or 10 years and the price difference.
- Excess: per claim and the total maximum.
- Add-ons: sewer, soil contamination, mould.
- Deadline: no later than the handover day.
The policy runs for 5 years, but some hidden problems (mould inside a wall, a slowly leaking sewer) only show after several years. The extra for 10 years (+50% in the offer we have seen) is often cheaper than a single such claim.
My view
I would take the insurance: the seller pays half anyway. But you should buy the house as if it did not exist. Count everything in the reports as your own cost and build it into the price. Then the insurance becomes a bonus, not a plan.
Yurii Khlivnenko, founder of NordIndsigt
On your own or with us?
You can read the reports and insurance terms yourself if you have the time and the Danish. The difficulty is elsewhere: in your first report it is hard to see which wording means a future dispute with the insurer. We have seen hundreds of these reports. And when you like the house, "not inspected" easily reads as a formality. We are not attached to the house, so with us you will know within 24-48 hours what the insurance will not cover, before you sign.
In short
The key question for the insurance: what of the things that can break is already written in the reports, and therefore not covered?
Want to know what in your house is already excluded from the insurance?
BoligCheck goes through the reports and shows what lands on you, with prices in two scenarios.
Order BoligCheck, DKK 299Frequently asked questions
What does ejerskifteforsikring cover?
Hidden damage that existed on the handover day and is not mentioned in the tilstandsrapport or the elinstallationsrapport. A typical basic policy runs for 5 years and can be extended to 10 (in a 2026 offer from one of the large insurers that cost 50% extra).
What does ejerskifteforsikring not cover?
The more red items in the report, the less the insurance protects you. A seller with an "honest" report where everything is written down effectively moves those risks onto you: they are already "known", and the known cannot be insured.
Why does ejerskifteforsikring reject so many claims?
It is the buyer who must prove the claim is covered. The hardest cases involve damp and mould: experts often disagree on the cause and on whether the damage existed before the purchase (Bolius).
What should you check before taking out ejerskifteforsikring?
The policy runs for 5 years, but some hidden problems (mould inside a wall, a slowly leaking sewer) only show after several years. The extra for 10 years (+50% in the offer we have seen) is often cheaper than a single such claim.
On your own or with us?
You can read the reports and insurance terms yourself if you have the time and the Danish. The difficulty is elsewhere: in your first report it is hard to see which wording means a future dispute with the insurer. We have seen hundreds of these reports. And when you like the house, "not inspected" easily reads as a formality. We are not attached to the house, so with us you will know within 24-48 hours what the insurance will not cover, before you sign.